Every state, city and ZIP
The Assumable Atlas
Assumable mortgages, by market
RetroRate's public, market-by-market view of assumable mortgages in the United States, built from RetroRate data covering every home in the country and updated monthly. About one in ten homes for sale with a mortgage comes with an assumable FHA or VA loan a buyer can take over at the seller's original rate. Nationwide there are 10,600,000 homes carrying one that aren't for sale, and roughly 120,000 assumable listings active at a time. Here's where they are, and what an assumable mortgage actually is.
RetroRate data as of November 9, 2026
National totals
- Homes with an assumable loan That aren't for sale
- 10.6M
- Assumable listings Active at any one time
- 120K
- average 30-year fixed rate As of Nov 13
- 7.25%
Where the inventory is
Every state, by the number of homes carrying an assumable FHA or VA loan. Savings are what the average loan in that state saves a buyer each month against a new loan at the market rate, at the same cash to close.
| Texas | 1,107,714 | 67.1% | 32.9% | 4.80% | $287 | Numbers from the MLS coverage areas in this region, and may not represent the entire state. |
|---|---|---|---|---|---|---|
| Florida | 965,128 | 65.6% | 34.4% | 4.82% | $318 | Numbers from the MLS coverage areas in this region, and may not represent the entire state. |
| California | 706,996 | 63.8% | 36.2% | 4.51% | $547 | |
| Ohio | 510,021 | 75.4% | 24.6% | 4.77% | $201 | |
| Georgia | 432,257 | 64.9% | 35.1% | 4.58% | $306 | |
| Pennsylvania | 421,829 | 79.0% | 21.0% | 4.70% | $224 | |
| Illinois | 411,371 | 79.9% | 20.1% | 4.65% | $246 | |
| Virginia | 396,172 | 48.0% | 52.0% | 4.52% | $428 | |
| North Carolina | 395,327 | 51.6% | 48.4% | 4.83% | $277 | Numbers from the MLS coverage areas in this region, and may not represent the entire state. |
| Maryland | 360,256 | 67.9% | 32.1% | 4.73% | $360 | |
| Tennessee | 325,721 | 65.6% | 34.4% | 4.92% | $241 | |
| Arizona | 314,440 | 61.1% | 38.9% | 4.77% | $339 | |
| Washington | 286,018 | 53.4% | 46.6% | 4.56% | $430 | |
| Michigan | 275,545 | 78.0% | 22.0% | 4.72% | $198 | |
| South Carolina | 271,993 | 60.0% | 40.0% | 4.83% | $290 | |
| New Jersey | 264,513 | 84.8% | 15.2% | 4.63% | $364 | |
| Indiana | 260,697 | 77.5% | 22.5% | 4.76% | $321 | |
| New York | 256,208 | 85.5% | 14.5% | 4.62% | $323 | |
| Colorado | 228,304 | 53.1% | 46.9% | 4.63% | $463 | Numbers from the MLS coverage areas in this region, and may not represent the entire state. |
| Missouri | 227,111 | 70.8% | 29.2% | 4.79% | $218 | |
| Oklahoma | 199,744 | 66.4% | 33.6% | 4.87% | $200 | |
| Alabama | 184,779 | 62.3% | 37.7% | 4.75% | $268 | |
| Nevada | 174,712 | 63.7% | 36.3% | 4.73% | $349 | |
| Minnesota | 147,450 | 70.8% | 29.2% | 4.55% | $297 | |
| Kentucky | 135,654 | 69.9% | 30.1% | 4.87% | $209 | |
| Arkansas | 125,255 | 66.7% | 33.3% | 4.82% | $212 | |
| Louisiana | 117,229 | 73.0% | 27.0% | 4.72% | $244 | |
| Oregon | 111,371 | 57.7% | 42.3% | 4.63% | $405 | |
| Wisconsin | 111,055 | 65.0% | 35.0% | 4.55% | $273 | |
| New Mexico | 100,274 | 65.3% | 34.7% | 4.76% | $405 | |
| Massachusetts | 91,547 | 87.5% | 12.5% | 4.45% | $465 | |
| Iowa | 85,188 | 67.2% | 32.8% | 4.75% | $203 | |
| Idaho | 82,638 | 60.3% | 39.7% | 4.74% | $333 | |
| Kansas | 77,463 | 64.8% | 35.2% | 4.67% | $227 | |
| Nebraska | 66,568 | 60.8% | 39.2% | 4.73% | $234 | |
| Mississippi | 60,952 | 67.8% | 32.2% | 4.85% | $254 | |
| Connecticut | 54,382 | 92.7% | 7.3% | 4.51% | $317 | |
| Delaware | 51,032 | 71.7% | 28.3% | 4.55% | $325 | |
| Alaska | 42,195 | 43.9% | 56.1% | 4.48% | $394 | |
| West Virginia | 39,307 | 64.2% | 35.8% | 4.86% | $225 | |
| Hawaii | 33,596 | 23.2% | 76.8% | 4.28% | $791 | |
| Montana | 32,448 | 53.1% | 46.9% | 4.76% | $311 | |
| Utah | 32,082 | 75.3% | 24.7% | 6.12% | $121 | |
| Maine | 27,913 | 75.2% | 24.8% | 4.63% | $283 | |
| Rhode Island | 27,631 | 90.8% | 9.2% | 4.54% | $371 | |
| Wyoming | 27,308 | 61.3% | 38.7% | 4.86% | $273 | |
| New Hampshire | 25,944 | 71.0% | 29.0% | 4.40% | $383 | |
| North Dakota | 23,478 | 62.2% | 37.8% | 4.67% | $270 | |
| South Dakota | 10,791 | 60.2% | 39.8% | 4.52% | $266 | |
| District of Columbia | 1,041 | 49.8% | 50.2% | 6.07% | $176 | |
| Vermont | 216 | 71.3% | 28.7% | 4.36% | $253 |
On-market coverage: live listing data includes what's for sale. Off-market coverage: counts of all homes with a mortgage carrying an assumable loan.
Where assumption saves the most
The markets where the gap between the loans people already hold and the loans a buyer would take out today is widest.
| Larkspur, CO | $912 | 4.26% | 195 |
|---|---|---|---|
| Ewa Beach, HI | $909 | 4.13% | 6,164 |
| Chula Vista, CA | $892 | 3.97% | 11,490 |
| Kapolei, HI | $876 | 4.11% | 3,142 |
| San Diego, CA | $861 | 4.06% | 21,458 |
| Elizabeth, CO | $854 | 5.20% | 1,318 |
| Honolulu, HI | $846 | 4.33% | 4,530 |
| Evergreen, CO | $830 | 4.23% | 417 |
| Parkland, FL | $825 | 4.23% | 279 |
| Boulder, CO | $816 | 4.32% | 318 |
On-market coverage: live listing data includes what's for sale. Off-market coverage: counts of all homes with a mortgage carrying an assumable loan.
On-market coverage
We publish counts of what's for sale in the markets where we license listing data. Everywhere else, the off-market counts stand on their own and VHS shows you what's listed.
| Colorado | Numbers from the MLS coverage areas in this region, and may not represent the entire state. | 14.5% |
|---|---|---|
| Florida | Numbers from the MLS coverage areas in this region, and may not represent the entire state. | 6.9% |
| Texas | Numbers from the MLS coverage areas in this region, and may not represent the entire state. | 15.6% |
| North Carolina | Numbers from the MLS coverage areas in this region, and may not represent the entire state. | 12.1% |
Size of the equity gap in the markets we cover
A buyer assuming a loan takes over its balance, not its asking price, so the gap between the two is what they bring to closing. That gap is the seller's equity, and it is the most common reason an assumption falls through. Here is how wide it runs across every market where we license listing data.
In the markets we cover, 47.8% of assumable listings have an equity gap under 20% of the asking price, and 31.2% under 10%.
See all equity bands in the markets we cover
| Equity gap | Share | At or below |
|---|---|---|
| Below -20% | 2.4% | 2.4% |
| -20% to -15% | 1.0% | 3.4% |
| -15% to -10% | 1.5% | 4.9% |
| -10% to -5% | 2.1% | 7.0% |
| -5% to 0% | 3.6% | 10.6% |
| 0% to 5% | 8.1% | 18.7% |
| 5% to 10% | 12.6% | 31.2% |
| 10% to 15% | 9.5% | 40.8% |
| 15% to 20% | 7.1% | 47.8% |
| 20% to 25% | 6.4% | 54.2% |
| 25% to 30% | 5.4% | 59.5% |
| 30% to 35% | 5.4% | 64.9% |
| 35% to 40% | 5.3% | 70.2% |
| 40% to 45% | 5.1% | 75.3% |
| 45% to 50% | 5.3% | 80.6% |
| 50% to 55% | 4.8% | 85.3% |
| 55% to 60% | 4.2% | 89.5% |
| 60% to 65% | 3.2% | 92.7% |
| 65% to 70% | 2.4% | 95.1% |
| 70% to 75% | 1.6% | 96.7% |
| 75% to 80% | 0.9% | 97.6% |
| 80% to 85% | 0.7% | 98.3% |
| 85% to 90% | 0.5% | 98.8% |
| 90% to 95% | 0.3% | 99.1% |
| 95% to 100% | 0.9% | 100.0% |
How to see them
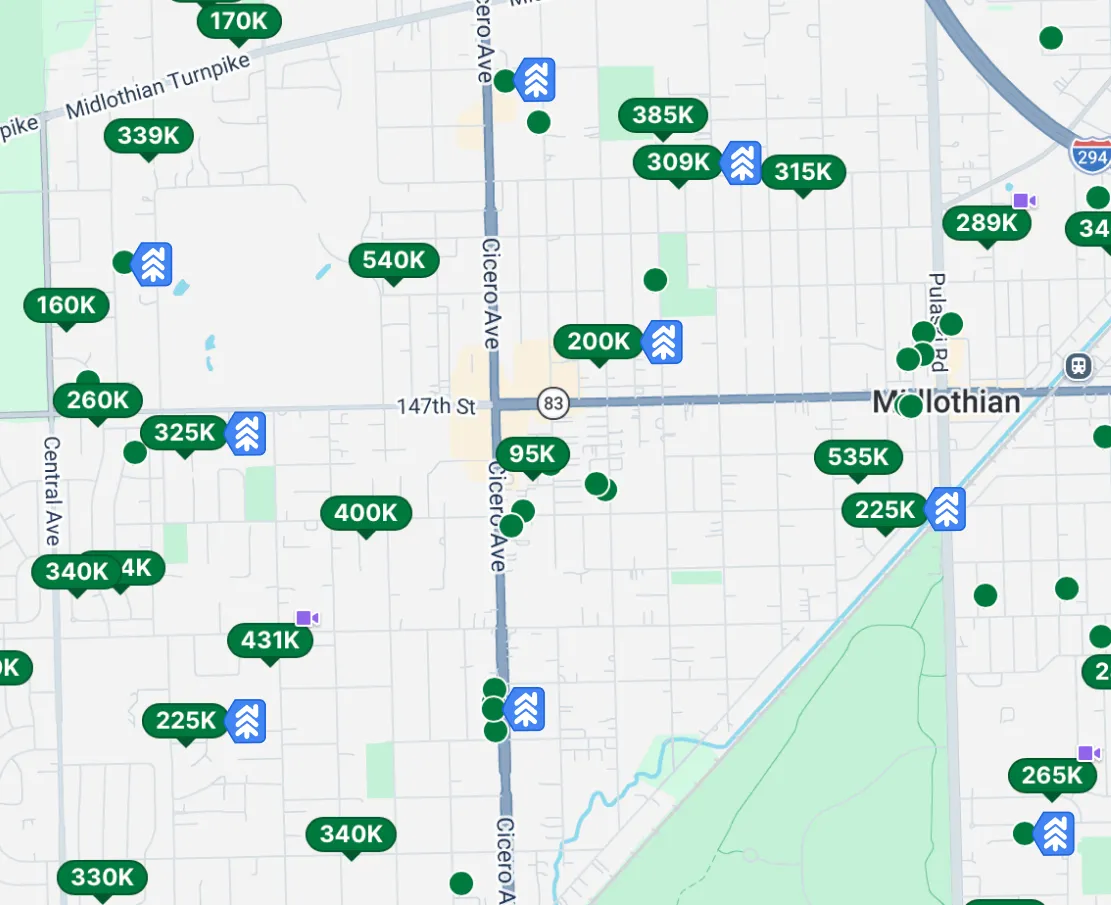
See which listings in your market come with an assumable loan, on the sites you already use. VHS is a free browser extension that flags them as you browse.
Every state
- Alabama
- Alaska
- Arizona
- Arkansas
- California
- Colorado
- Connecticut
- Delaware
- District of Columbia
- Florida
- Georgia
- Hawaii
- Idaho
- Illinois
- Indiana
- Iowa
- Kansas
- Kentucky
- Louisiana
- Maine
- Maryland
- Massachusetts
- Michigan
- Minnesota
- Mississippi
- Missouri
- Montana
- Nebraska
- Nevada
- New Hampshire
- New Jersey
- New Mexico
- New York
- North Carolina
- North Dakota
- Ohio
- Oklahoma
- Oregon
- Pennsylvania
- Rhode Island
- South Carolina
- South Dakota
- Tennessee
- Texas
- Utah
- Vermont
- Virginia
- Washington
- West Virginia
- Wisconsin
- Wyoming
Assumable mortgages, by market: common questions
General questions about assumables live on the FAQ.
- What is the Assumable Atlas?
-
The Assumable Atlas is RetroRate's public, market-by-market view of assumable mortgages in the United States, built from RetroRate data covering every home in the country and updated monthly.
It doesn't show listings. It shows how many there are, where, and what they're worth to a buyer.
Want to use this data in an article?
Assumable loans are a good way to show the deals hiding in the markets you write about, and most of them are never mentioned in the listing. We can cut these figures however your story needs them: one city, one ZIP code, or a few markets side by side.
RetroRate's public, market-by-market view of assumable mortgages in the United States, built from RetroRate data covering every home in the country and updated monthly. Cite it as the Assumable Atlas by RetroRate.
For a custom report or a deep dive, email press@retrorate.com. See our press page for current and historical coverage.
For agents and brokers
Agents and brokerages use RetroRate to find, verify and market the assumable loans in their market, in any market they operate in.
Our methodology
Every page in the Assumable Atlas is built from the same monthly RetroRate data drop. Counts cover homes with an assumable FHA or VA loan, whether or not they're for sale, as of November 9, 2026. They come from public data sources and county records.
Savings compare the assumable loan's payment with a new loan for the same amount at the average 30-year fixed rate of 7.25%, as of November 13, 2026, at the same cash to close. Principal and interest only: taxes, insurance and mortgage insurance vary and aren't included. A buyer still qualifies with the loan's servicer. Rate provided by Optimal Blue Mortgage Market Indices (OBMMI).
The 10,600,000 homes with an assumable loan that aren't for sale and the roughly 120,000 assumable listings active at a time are RetroRate's own production data. "About one in ten homes for sale with a mortgage" is RetroRate's count of listings carrying an assumable FHA or VA loan.
The per-market counts on these pages are every home carrying an assumable loan in that place, listed or not, so they add up to more than the 10,600,000 above: that figure takes the listed homes out.