For agents
Sell the loan that comes with the house.
When nobody can get a good rate, a listing that carries one stands out. RetroRate tells you which of your listings has an assumable loan, verifies its details so you can advertise the rate with confidence, and gives you the marketing to put that rate in front of buyers.
Live to over 180k agents; available nationwide to all brokerages.
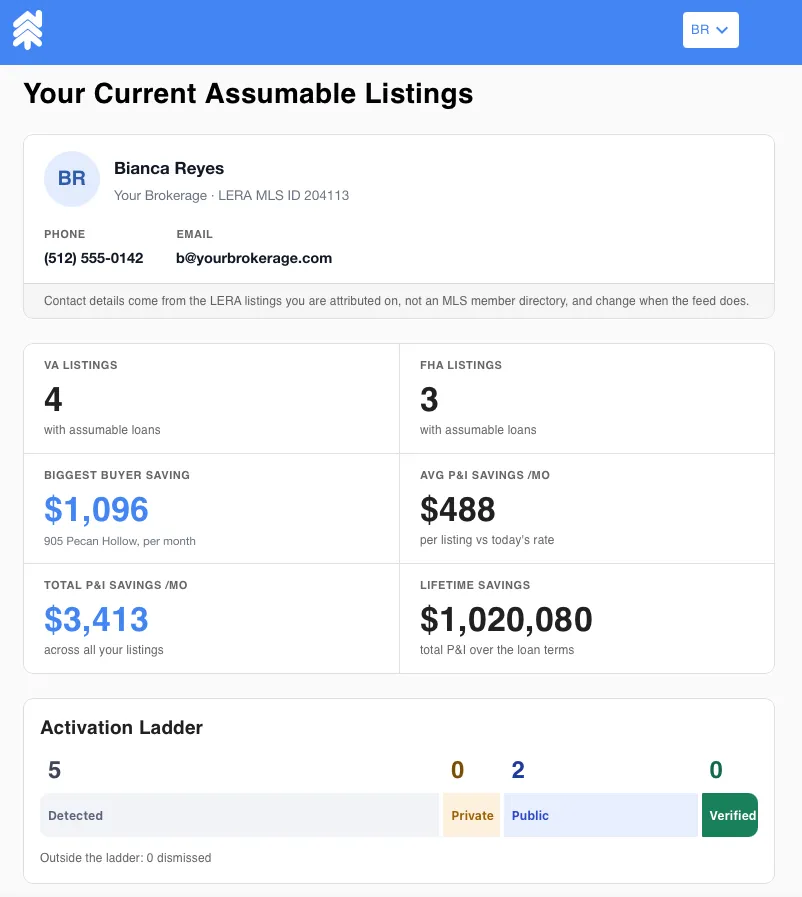
Find it. Prove it. Show it.
-
1 Find
Every assumable listing in your market, ranked by RetroMatch™, our score for how much a loan could save a buyer.
-
2 Verify
We cross-reference the seller's mortgage statement against a variety of data sources to confirm accuracy, then issue a Verification of Loan (VOL) report.
-
3 Market
Show buyers the assumable payment next to a new loan at today's rates, at the same cash to close.
Everything you need to work an assumable listing
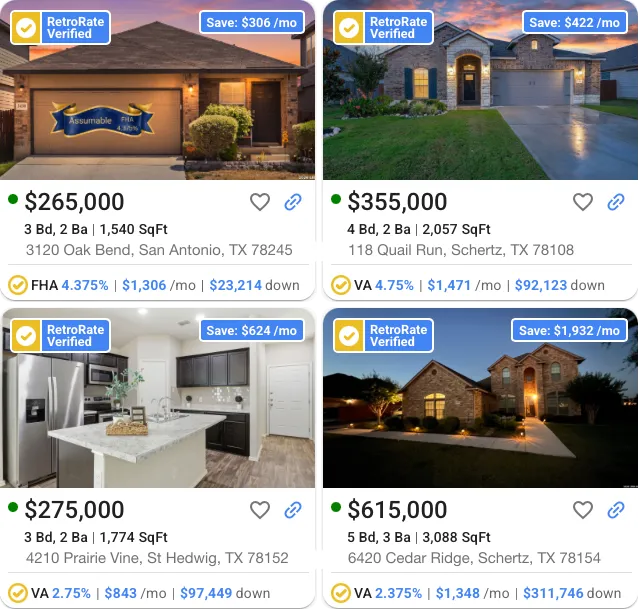
Every assumable listing in your market
Search them all in one place instead of digging through remarks for the word "assumable." It's not unusual to see 20x the number of actual assumable deals.
RetroMatch™ weighs the rate, the balance, and hundreds of other attributes to help you decide what to focus on first. Win more listings with a tailored listing presentation that focuses on the great rate a home carries, rather than the stainless steel appliances.
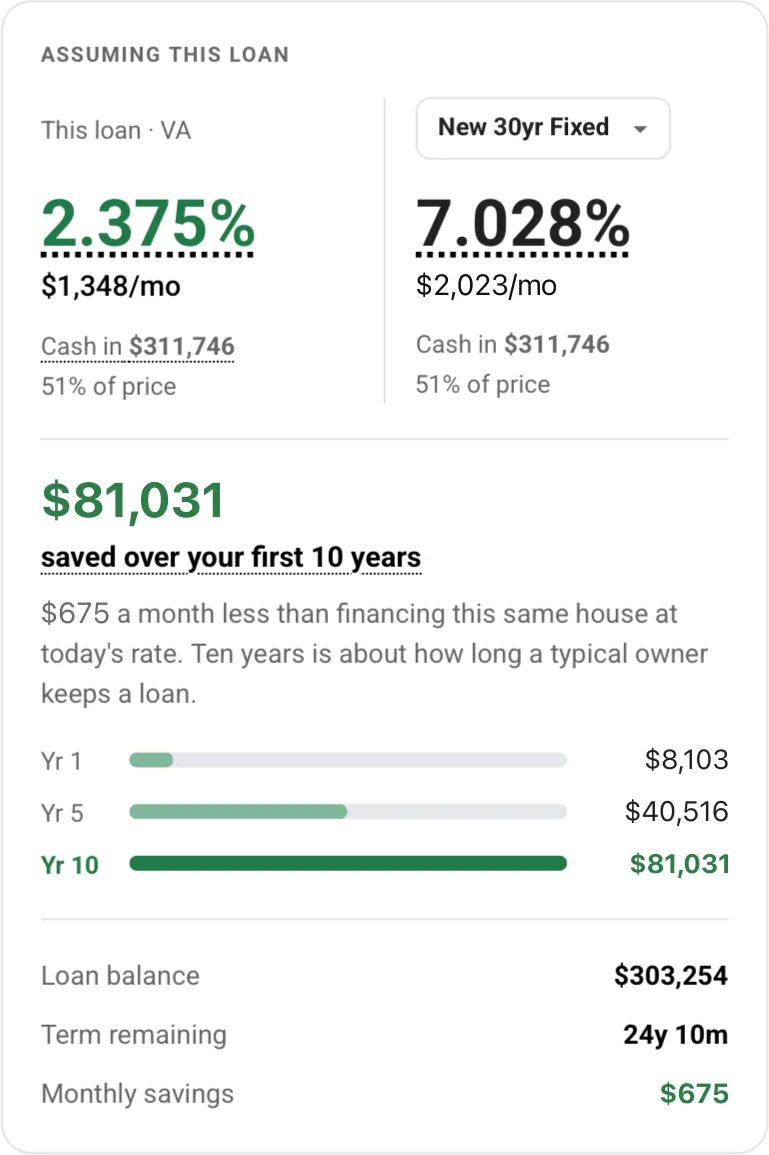
Show buyers the real difference
RetroRate analyzes and compares the assumable loan next to a new loan at today's rates with the same cash to close. We'll show you the tradeoffs in down payment and monthly savings across a variety of loan types, so you can help guide your buyer.
RetroRate Verified
Prove the rate before you advertise it.
We cross-reference the seller's mortgage statement against a variety of data sources to confirm accuracy, then issue a Verification of Loan (VOL) report. The listing carries the Verified badge the whole time it's active, and you can share the VOL report to show you've done your homework.
Heard from the industry
Winning clients when buyers guard their privacy
Homebot put the question to a panel RetroRate sat on: privacy rules and affordability are changing how buyers search, so what does an agent do about it? Our answer is the one nobody else can make, a rate they can't get anywhere else.
Questions agents ask
How do I set expectations with a buyer and seller?
Four things to say up front:
- Timeline. Thirty to forty-five days is common, and it varies by servicer.
- The buyer still qualifies. Income, assets, employment, credit and debt-to-income, the same as any loan.
- The seller comes off the loan when the release is issued. The servicer approves the buyer, then releases the seller. Expect it, but treat it as a step in the deal rather than a formality, and get the release in writing.
- Mind the equity gap. Where the home is worth more than the loan balance, the buyer covers the difference in cash or with a second loan.
How do I confirm that my listing is assumable?
A pre-listing check checks assumability, rate, terms and loan type against our database of assumable listings nationwide.
To put the rate in your marketing, verify it: we cross-reference the seller’s mortgage statement against a variety of data sources to confirm accuracy, then issue a Verification of Loan (VOL) report. Start that from the pre-listing check or your listings dashboard.
Why should I offer mortgage assumption as an option when selling a home?
An assumable loan opens the listing to buyers who can’t reach the payment on a new loan. If you want a line of buyers down the block at your open house, promote the rate.
It also appeals to buyers staying conservative on monthly payment, who would rather not stretch past a target price.
Can I sell a home at a higher price if the mortgage is assumable?
You aren’t only selling the home, you’re selling the home with its mortgage. The right to convey the loan is written into the mortgage contract, and while rates are where they are, it’s a marketing point worth making.
It gives you leverage in negotiation and drives foot traffic, which is what creates demand.
What's needed from my seller?
One recent mortgage statement, as an image or PDF. You can upload it yourself, or send your seller a secure link to upload it.
How does RetroRate verify a loan?
We cross-reference the seller’s mortgage statement against a variety of data sources including public records and county recorder information to confirm accuracy, then issue a Verification of Loan (VOL) report.
Is this safe and secure?
Our system uses the statement for verification only. It’s deleted automatically as soon as verification is complete.
What loans qualify?
VA and FHA loans are assumable and supported on RetroRate.
More from RetroRate
RetroRate Verified
Verify details of an assumable loan, and promote your listing to agents looking for assumable deals on and off RetroRate.
VHS Extension
Download RetroRate VHS: A free browser extension that shows you assumable loan information on top of your favorite real estate portals and broker sites.
Developer API
Integrate RetroRate's proprietary assumable loan database and intelligence platform directly into your own site.

See the assumable listings in your market.
In thirty minutes we'll give you the rundown on assumable loans and show how you can leverage assumable data in your own listings.
"20x the number of actual assumable deals" is based on RetroRate production data and MLS outcomes observed in 2026.