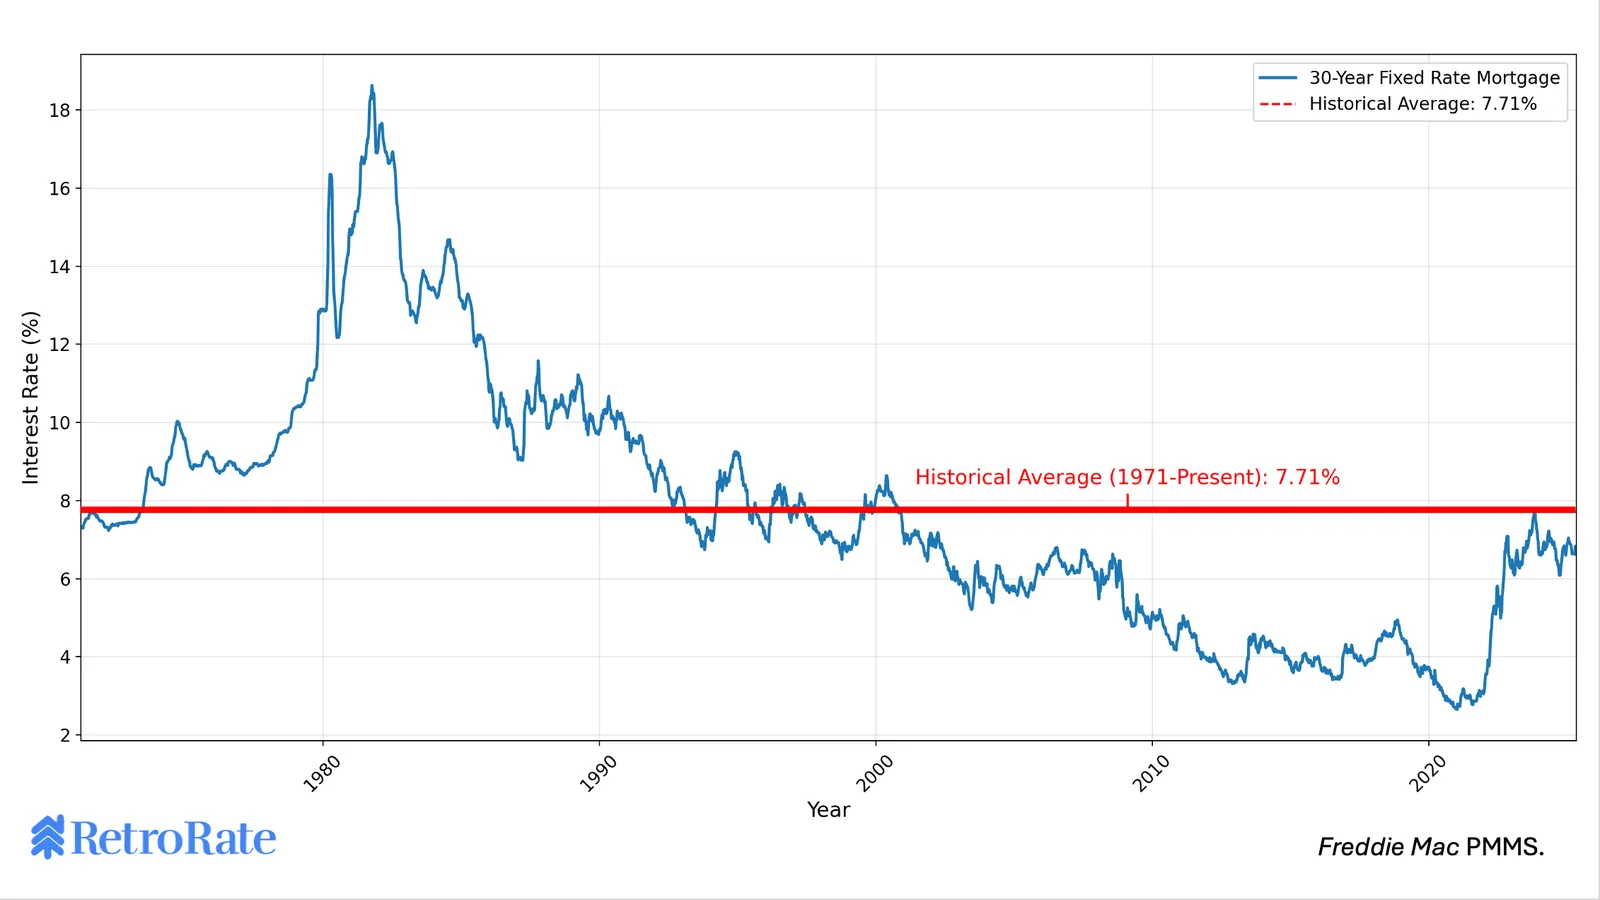
Stop Waiting for the Fed
Push Rewind on Assumable Loans
By Andy Taylor
Eligibility
Theoretically, any buyer can assume an FHA or VA loan, as long as they qualify and meet eligibility requirements. You don't have to be a veteran to assume a VA loan, and you don't have to be a first-time buyer to assume an FHA one. Two things decide it: whether the servicer approves you, and whether the loan program expects you to live in the house.
Loan by loan
| Loan | Can a buyer assume it? | Who can assume it | Does the seller's rate carry over? |
|---|---|---|---|
| FHA | Yes | Any buyer the servicer approves. Not only first-time buyers. Must occupy the assumed home | Yes |
| VA | Yes | Any buyer the servicer approves. You don't have to be a veteran. No occupancy requirements, so open to investors | Yes |
| USDA | Yes, with the agency's approval | A buyer the agency approves | Usually not: most USDA assumptions reset to current rates and terms |
| Conventional | Almost never | Narrow cases only, such as death, divorce, or marriage | Not applicable |
| Some ARMs | Sometimes | Depends on what the note says | Until the rate next adjusts |
FHA and VA loan assumptions transfer the original mortgage rate, which is why they're the two loan types that RetroRate covers.
Conventional mortgages can't usually be assumed, and it comes down to one clause written into the mortgage contract. A conventional loan carries a "due-on-sale" clause, which lets the lender demand the whole balance the moment the house changes hands, or is sold. This allows the lender to protect its position in the loan. A loan written at 3% is worth less to them than the same money lent at today's rate, so they would rather that loan be paid off and write a new one at today's rates.
By design, FHA and VA loans don't carry that clause. These loans are insured or guaranteed by the federal government, which takes most of the default risk off the lender. In exchange, the FHA or VA sets the terms, and those terms say a creditworthy buyer can take the loan over. Assumability is part of what a lender agreed to in order to write a government-backed loan in the first place, and it helps the federal government meet its mandate of getting more people into homes.
USDA loans are an exception to this. They can be assumed, but the agency has to approve the transfer first, and most USDA assumptions reset to current rates and terms, making them less attractive to most buyers.
An assumption is underwritten like a new loan would be. The servicer looks at similar things to a new lender: credit history, income, what else you owe, and whether you can cover the monthly payment. Generally speaking, if you'd qualify for a new loan at today's higher rate, you'll usually clear the bar on an assumption at a lower one, because the payment you have to carry is smaller. You still have to go through the process to be sure, though.
On an FHA loan the automated scorecard isn't allowed, so a person underwrites it by hand. That's part of why servicers quote long timelines.
While a non-veteran can assume a VA loan, it locks up the seller's VA benefits attached to their Certificate of Eligibility (COE) in the home. The benefits remain tied to the original loan, and unless the seller can find another veteran to buy the home and "substitute" their own eligibility instead, the seller can't use a VA loan until the home sells or is refinanced.
This may not be a problem if the seller isn't planning to use their full entitlement on their next purchase, or isn't buying a new home at all. Though it often means a veteran seller will only consider offering an assumption to other veteran buyers. Either way, the veteran seller should know what they're giving up before they accept the offer. It's a common reason a VA assumption doesn't take place.
Everything we've already discussed prior has been about an arms-length sale. When a house moves between family members, federal law changes the rules a bit. A lender generally can't call a conventional loan due because of a transfer on death, a divorce settlement, a transfer to a spouse or child, or a move into a living trust.
That's a protection against the due-on-sale clause rather than a right to assume, and the practical steps vary by servicer. If that's your situation, the loan type matters less than the paperwork, and it's worth asking an attorney and the servicer what they need before anything is signed.
You have to meet the current VA or FHA requirements. That usually means a credit score of at least 580, though around 620 is preferred, and a debt-to-income ratio under 50%. As with any loan, your package shows income, savings and employment.
A VA loan. You don’t have to be a veteran to assume one, though not every veteran will allow a non-veteran to, because it ties up their entitlement. Investors can sometimes assume a VA loan without living in the home.
An FHA loan. You attest that the home will be your primary residence for the next year, and you’ll likely need to move in within 60 days of completing the assumption.
No. The lender or servicer holding the mortgage handles qualification and approval, usually working with the VA or FHA. RetroRate takes no part in loan or credit decisions.
You still have to meet the VA or FHA requirements: a credit score of at least 580, with around 620 preferred, and a debt-to-income ratio under 50%.
The limit is the balance left on the existing mortgage, which can’t be increased or changed. Anything above that is cash or a second loan.
Push Rewind on Assumable Loans
By Andy Taylor
Let’s get it out in the open. You’re sitting on a goldmine if you have an assumable FHA or VA loan and you’re about to sell your house.
By Greg Fischer
In 2023, only 2,244 VA loans were assumed, out of roughly 350,000 VA-financed homes that turned over as resales. That’s less than 1% of the volume.
By Greg Fischer

The extension marks them while you browse the listings you're already looking at.
Occupancy on an assumption is set by each program, not by RetroRate. A buyer taking over an FHA loan has to be approved as a substitute mortgagor and occupy the home as a principal residence or a HUD-approved secondary residence (24 CFR 203.258(b) and 24 CFR 203.512(c)), which is the rule for loans insured on or after 15 December 1989. The VA's assumption statute sets three conditions, that the loan is current, that the buyer is contractually bound, and that the buyer is creditworthy, and imposes no occupancy requirement (38 U.S.C. 3714(a)(1)). A veteran who substitutes their own entitlement is doing something different, and the VA's occupancy rules apply to them.
The rules above come from the agencies that set them, not from RetroRate. FHA assumption policy is in HUD Handbook 4000.1, and the VA's is in its own lender guidance. Protections for family transfers of a conventional loan come from the Garn-St Germain Depository Institutions Act of 1982. A servicer's own overlays can be stricter, and state law can change the detail.
RetroRate does not originate loans, determine or extend credit, or engage in lending or mortgage brokering. The original lender or servicer who holds the mortgage handles qualification and approval of new buyers and makes the final decision to extend credit.