Don’t Sleep on Your Assumable Loan: A Seller’s Guide to Cashing In

By Greg Fischer
Head of Growth
Let’s get it out in the open. You’re sitting on a goldmine if you have an assumable FHA or VA loan and you’re about to sell your house.
Your low-rate loan isn’t just a perk, it’s a product. And you’re the dealer.
Done right, this could save your buyers hundreds or thousands per month, increase your sale price, and fund more vacations or savings for both.
Step Up and Own It
Assumable loans are rare, powerful, and criminally underused. Only a fraction of agents know how to handle them, and most sellers don’t even realize what they’re holding.
But you’re not most sellers. You’re about to turn your 3% loan into a six-figure flex. Here’s what you do, step by step, to make your assumable loan become the star of the sale and take full advantage of the benefit.
- Dig Up Your Mortgage Details
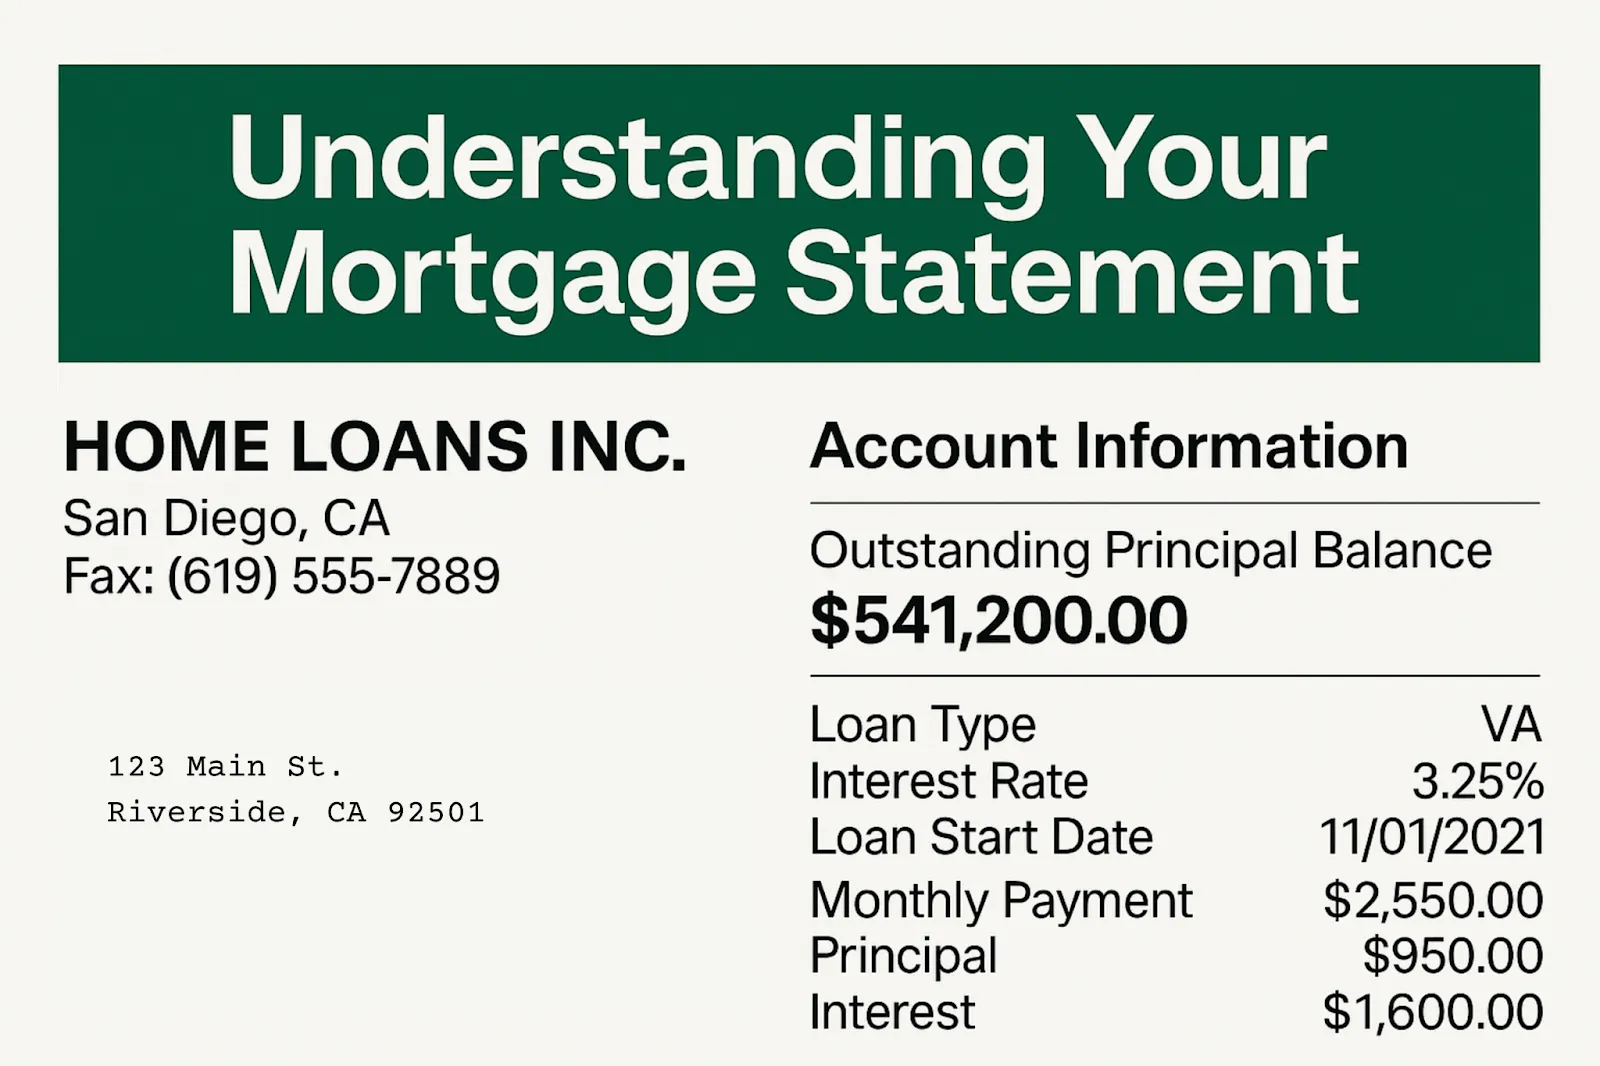
Grab your latest mortgage statement. Check your pile of mail or online portal. This shows your loan balance, interest rate, and monthly payment. It’s only a rough sketch, so don’t stop there.
- Talk to the Right People
Contact your loan servicer and ask for their assumable loan department or specialist. General reps won’t cut it. You want someone who knows the ins and outs. Confirm your loan’s details again. The interest rate, balance, remaining term, and that it’s assumable. Get a clear timeline of the assumption process, including any paperwork you can start now.
- Lean on RetroRate
Got questions? Confused by what the servicer told you? Hit us up at RetroRate. We’ll double-check the details, clarify the process, and make sure you’re not winging it.
- Hire a Sharp Agent
Interview agents and pick one who’s ready to learn. Most haven’t touched an assumable loan, but we’ll get them up to speed. A great agent + RetroRate’s know how = a deal that maximizes your leverage.
- Crunch the Numbers
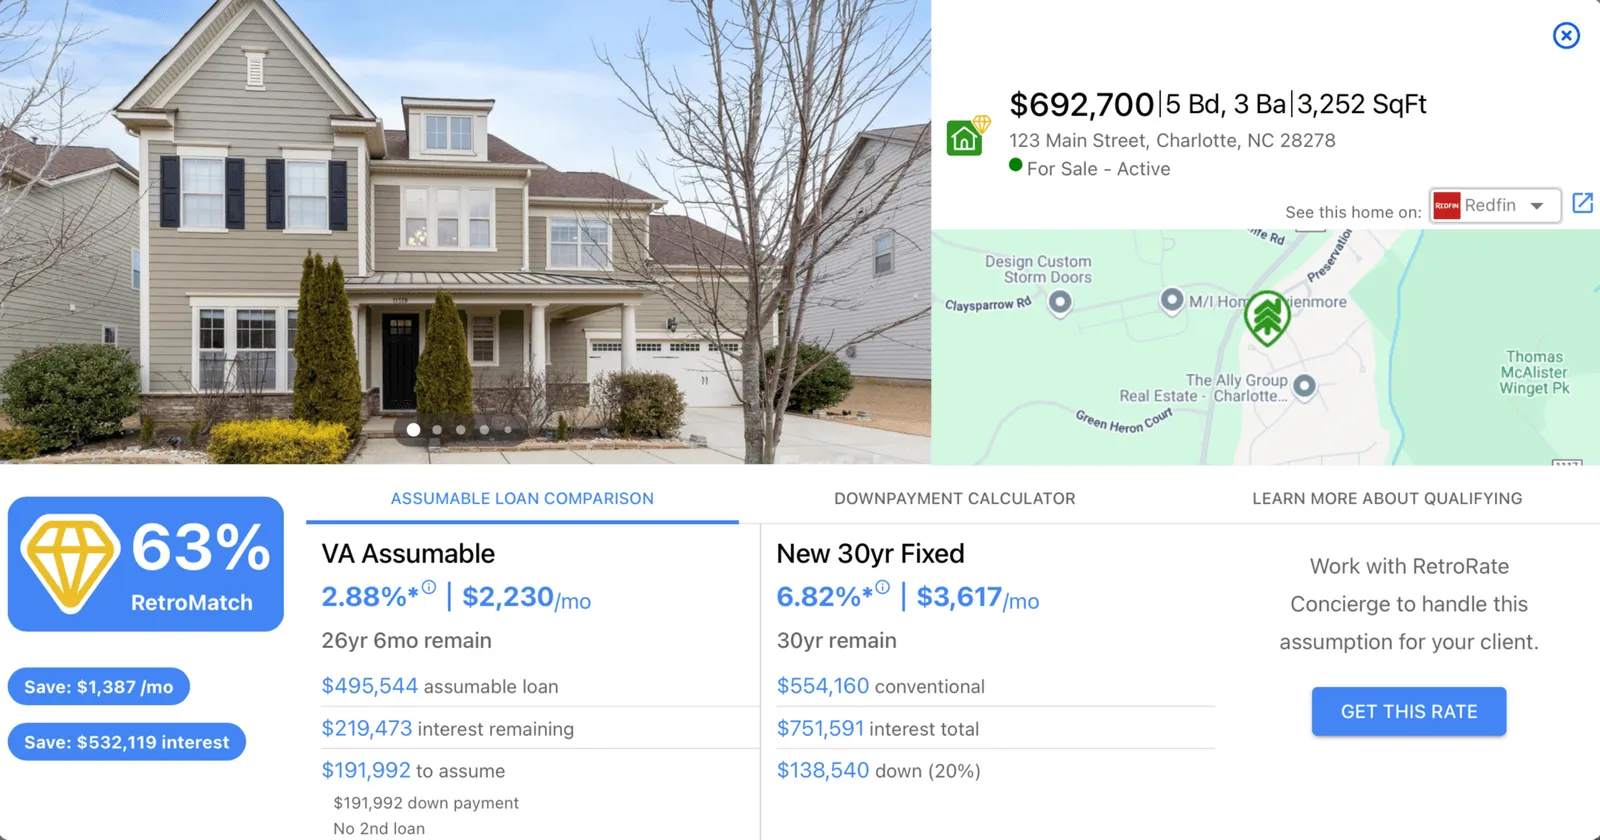
Compare your loan’s monthly payment to what a buyer would pay at today’s 30-year fixed rates (spoiler: they’re brutal). The difference is hundreds, maybe thousands, monthly in savings. A selling superpower. A buyer assuming your loan could save hundreds of thousands over the full life of the loan. That’s not pocket change; it’s your negotiating edge. Need help with the math? RetroRate will run the numbers and build you a report.
- Market It Like a Product
You’re not just selling a house; you’re reselling a low-rate loan. Work with your agent to craft marketing materials that scream value. Highlight the savings. Monthly, yearly, and over the loan’s life. Show buyers just below your price point how your loan makes your home affordable. Educate other agents about the assumption process so their buyers don’t miss out.
- Get Ahead of the Game
Start the assumption paperwork before your home hits the MLS. If your pricing and positioning are on point, buyers will come fast. You don’t want to be scrambling when offers roll in. Preparation = power.
If you’ve got a VA loan, anyone can assume it, veteran or not, even investors. But it ties up your VA entitlement unless a veteran buyer swaps theirs in. Want the full scoop? Check our explainer here. RetroRate can walk you through the details.
Why This Matters
Your assumable loan isn’t just a line item; it’s a ticket to a better deal. Buyers not only save monthly, but shave years off their loan term. You get a higher price, stronger terms, and the chance to stand out in a crowded market. But it’s not automatic. Treat this like the six-figure project it is. Most sellers snooze on this opportunity, but you’re wide awake.
Ready to Make Moves?
Don’t let your low-rate loan gather dust. Contact RetroRate today. We’ll crunch the numbers, answer your questions, and help you and your agent sell this thing like the treasure it is. Assumable loans are the market’s hidden gems, and we’re here to make sure yours shines.
By Greg Fischer
Head of Growth
20yrs of startup grit, enterprise tech, and real estate brokerage. Navy Veteran.
Greg Fischer on LinkedIn