Homebuyers are dazzled by a property’s sleek finishes and high-end fixtures long before they hear about the one thing that could truly shift the equation: a better interest rate. With an assumable loan, a new buyer can take over a record-low interest rate directly from the seller.
A RetroRate analysis found that of the homes on our platform with an assumable loan, less than .1% actually marketed their home as having one. Talk about a missed opportunity!
A loan assumption is far less likely to happen if a listing is not actively promoted as assumable from the very beginning. The time to discuss whether a seller has an assumable FHA or VA loan is at the start, in the first conversation, but no later than at the listing appointment.
While agents typically review outstanding mortgage obligations with a seller, they often focus on the remaining balance rather than the loan type, its assumability, or the current interest rate. Yet, these details have major implications for how marketable a home’s assumable status can be. After all, you are not only selling the home but also the loan that comes with it.
Beyond understanding the basics of an assumable loan, agents should have upfront conversations with sellers about how the assumption process works. This includes contacting the loan servicer to confirm the loan’s assumption status, obtaining contact information for the department handling assumptions, and clarifying any pre-marketing steps or forms the servicer might provide.
Having this information ready ensures sellers are prepared when a buyer expresses interest in assuming the loan.
Expanding Opportunities for Buyers and Sellers
This preparation is especially critical in today’s market, which has cooled significantly from pandemic highs. With overall demand in homebuying down compared to recent years, sellers and agents might overlook a loan’s assumable status, prioritizing any buyer over a more strategic approach. This mindset misses the bigger picture: an assumable loan expands the buyer pool by increasing affordability.
For example, assuming a low-rate mortgage can save buyers hundreds to over a thousand dollars per month compared to taking out a new loan at today’s higher rates. This savings can stretch a buyer’s budget by $50,000 to $100,000 or more. A buyer previously shopping around $400,000 might now afford a home listed closer to $500,000. With assumptions, buyers can either get more house for the same monthly payment or a lower payment for the same house.
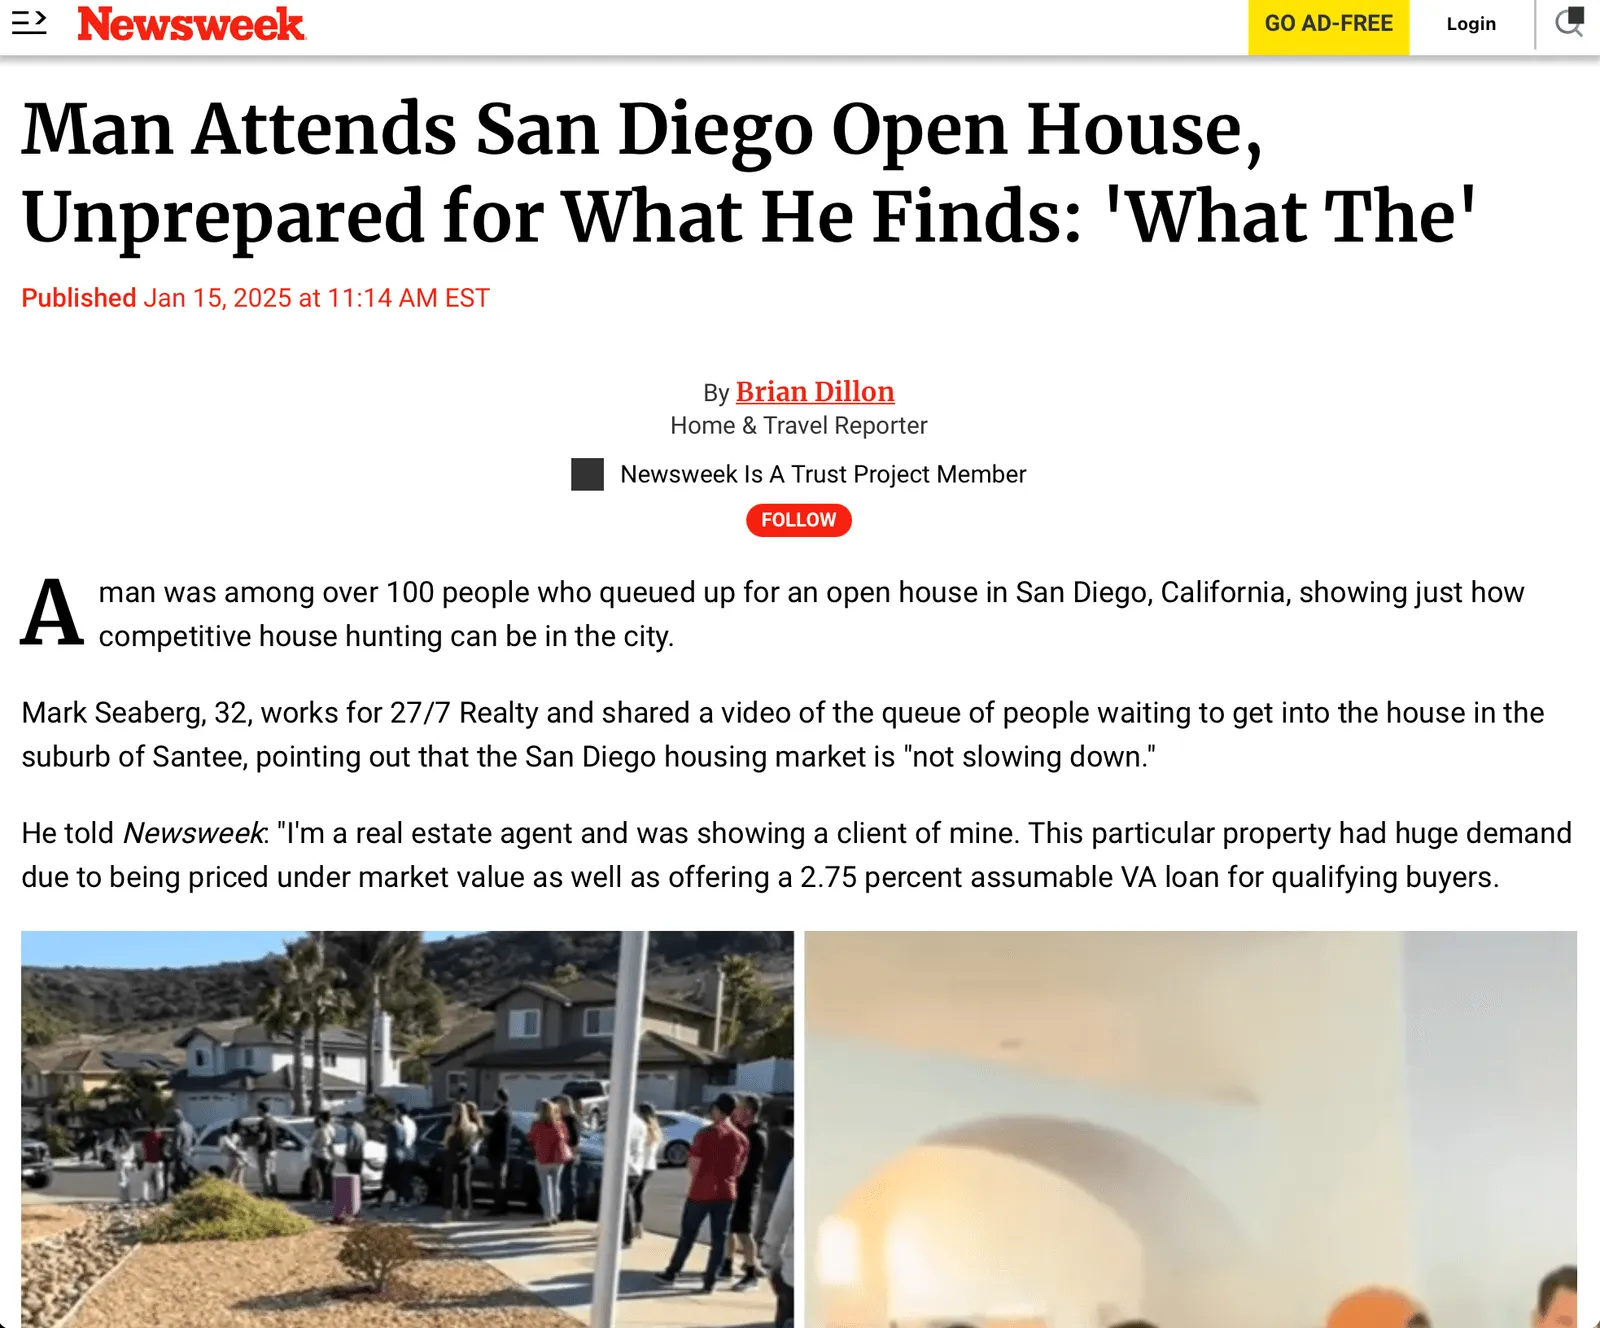
This is a game-changer for sellers, opening their listing to more potential buyers. If you are a listing agent and want a line of buyers stretching down the block to your open house, you should absolutely be promoting your assumable loan. It also appeals to buyers who want to stay conservative with monthly payments and avoid stretching beyond a target price range.
Yes, there are additional considerations, like the need for a down payment to cover the gap between the purchase price and the assumable loan balance, or the extra time required for loan servicer processing. But these are small hurdles compared to the benefits. For sellers, an assumable loan creates a larger, more competitive audience for their listing. For buyers, assuming a low-rate loan instead of securing a new one at today’s higher rates can save hundreds or thousands of dollars monthly.
At RetroRate, we are building software to turn every agent into an assumable loan expert. We help you find and prospect homes with assumable loans and give you the guidance needed to stand out in a competitive market. By helping agents identify and market assumable loans, we are empowering sellers to shine in a crowded landscape and connecting buyers with savings that make owning a home more attainable.

By Greg Fischer
Head of Growth
20yrs of startup grit, enterprise tech, and real estate brokerage. Navy Veteran.
Greg Fischer on LinkedIn